

Navy Federal Credit Union
by Navy Federal
3.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
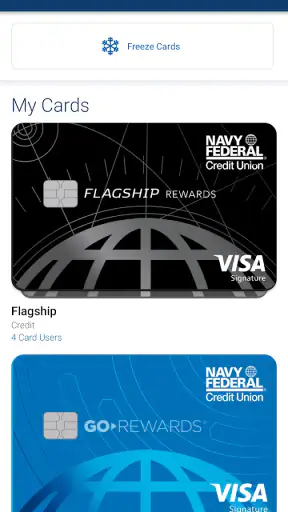
 Analysis by Getfullapps
Choosing a mobile banking app is less about finding the flashiest interface and more about deciding which financial relationship you want to manage from your phone. I spent time looking at Navy Federal Credit Union as a daily finance app, and my impression is clear: it makes the most sense for people who already belong to Navy Federal and want their credit union accounts close at hand. It is free, aimed at an Everyone audience, and developed by Navy Federal, so the main question is not whether it can replace every financial tool, but whether it fits the way you already bank.
This is a finance app rather than a general budgeting service, investment platform, or comparison marketplace. That distinction matters. If your priority is checking balances, keeping track of transactions, and handling ordinary account tasks without visiting a branch, the app belongs on your shortlist. If you want one neutral dashboard for several unrelated banks, detailed spending analysis, or a broad financial planning system, you may prefer a different category of app.
What I considered before recommending it
My first decision criterion was membership. Navy Federal is not simply a generic banking utility that works the same way for everyone. Its value is tied to the Navy Federal relationship, so someone who already uses the credit union starts with a practical advantage. A person who has no reason to open or maintain an account there may find that installing the app alone does not solve anything.
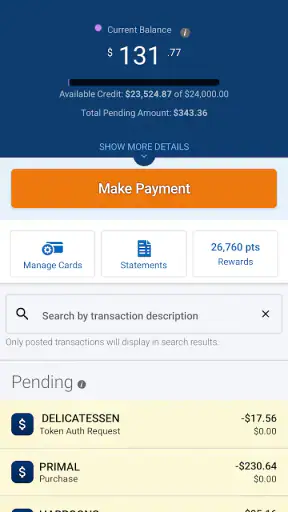
The second criterion was everyday usefulness. I looked at whether the app feels like something I would open during normal routines: checking whether a payment cleared, reviewing a recent purchase, confirming available money before moving funds, or handling a banking task while away from a computer. Those moments are more important to me than a long list of features I would rarely touch.
I also weighed trust and longevity. The app has been available since late July of 2011, and its current version is 2026.8.1. Its Android requirement is version 11 or newer, which is reasonable for many current phones but still worth checking before installing on an older device. The app has a 3.7 average from around 110 thousand ratings, with more than 10 million installs. That reach suggests it is an established mobile banking option, while the rating also reminds me not to describe it as flawless.
Finally, I considered switching friction. A mobile banking app is only useful when it connects smoothly to the accounts, habits, alerts, payment routines, and authentication steps I already depend on. Moving from one bank to another is not the same as replacing a weather app. Even when the download is free, changing where money arrives and bills are paid takes planning.
The best starting point is your existing Navy Federal relationship
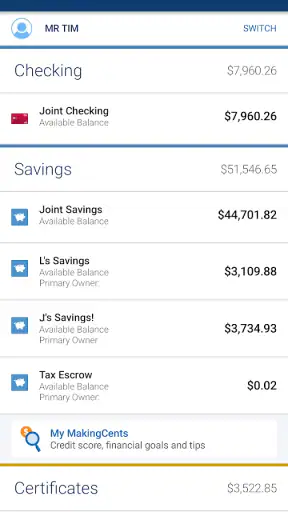
For an existing member, the app has a straightforward purpose: bring the credit union relationship into a pocket-sized control panel. That can reduce the need to use a desktop browser for simple checks and makes it easier to act when timing matters. I would particularly value that convenience when traveling, waiting in a queue, or reviewing finances at the end of a busy day.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The app is also a sensible choice for households that want a direct connection to their Navy Federal accounts rather than a separate money-management layer. A third-party budgeting app can be helpful, but it adds another service between you and the institution holding your money. Using the credit union’s own app keeps the primary account relationship in one place, which is simpler for basic account supervision.
Where the app earns its place in a daily routine
My favorite use case is a quick pre-purchase check. Imagine I am about to pay for groceries after several automatic payments have gone through. Instead of guessing from memory, I open the app, review the current account picture, and look at recent activity. That small habit can prevent an avoidable mistake and is exactly the kind of task a banking app should make easier.
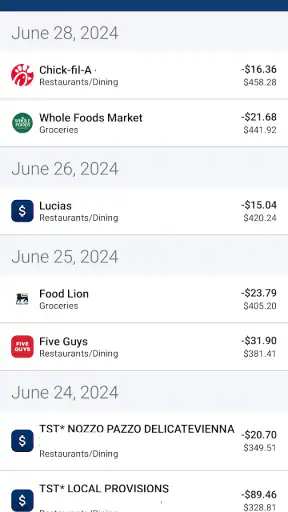
Another useful routine is checking transactions soon after using a card. I prefer catching an unfamiliar charge early, while the details are still fresh, rather than discovering it weeks later during a statement review. The app is well suited to that kind of frequent, short visit. It does not need to become a place where I spend half an hour every morning; it needs to give me confidence when I need a current view.
A less obvious benefit is using the app as a timing tool rather than only a record keeper. Before moving money, paying a bill, or making a larger purchase, I can verify the account situation instead of relying on an old balance written in a notebook. That is especially helpful for people whose income and recurring expenses arrive on different schedules.
I would also use it during travel as a quick point of reference. Travel often creates unusual spending patterns, and the ability to review activity from a phone is more practical than saving every receipt and waiting until returning home. I still would not treat a banking app as a replacement for careful travel planning, but it can make monitoring less stressful.
Small habits that make the experience more useful
I recommend opening the app with a specific question in mind. “What is my current balance?” “Did that transaction appear?” and “Do I have enough available money for this payment?” are better prompts than browsing aimlessly. This keeps mobile banking focused and reduces the chance of making a decision based on a quick glance without understanding which account or transaction you are viewing.
I would also build a regular review habit around transaction descriptions, not just the headline balance. A balance can look normal while a recurring charge has quietly changed or an expected payment has not appeared. Looking at activity gives a more realistic picture of what is happening. This is a practical strength of having direct account access, but it depends on the user actually checking details.
For shared household finances, I would agree in advance on who checks what and how often. The app can make access convenient, but convenience does not automatically create a clear household system. A short weekly review of recent activity may be more useful than several anxious checks each day, particularly when multiple people use the same accounts.
What the rating tells me, and what it does not
The 3.7 average from around 110 thousand ratings places the app in a middle ground. I would not use that number as proof that it is unreliable, but I also would not dismiss the complaints that often accompany banking apps. Financial software is judged during stressful moments: a login problem, a delayed transaction, an unfamiliar screen, or a device change can feel much more serious than a minor issue in a casual app.
The large install base shows that Navy Federal has become a familiar mobile channel for many users. Still, popularity cannot tell me whether the app matches my phone, my account needs, or my tolerance for authentication steps. I would install it with realistic expectations: it should support ordinary banking, but no mobile interface removes the need to read transaction details and protect account access carefully.
Where a different type of app may fit better
The biggest alternative is the traditional desktop or mobile website. A browser may be preferable when I am doing a longer financial review, comparing several statements, or working on a larger screen. The app wins for quick access, while a browser can feel more comfortable for extended sessions. I would not force myself to use the phone for every banking task simply because the app exists.
A second alternative is a multi-bank money manager. That category is better for someone who keeps accounts at several institutions and wants a combined view of balances and spending. Navy Federal’s app is more focused: it serves the Navy Federal relationship rather than acting as a neutral command center for an entire financial life. If consolidation is your main goal, another tool may reduce the need to switch between institutions.
Budgeting software is another different option. A dedicated budget app may offer stronger planning workflows, category-based analysis, or long-term targets, depending on the product. I would choose that route if my main problem were understanding spending patterns rather than accessing my credit union account. The Navy Federal app can be part of that system, but I would not assume a bank app should replace a purpose-built budget.
People who want investing research, credit monitoring across providers, or broad financial planning should also compare categories carefully. A credit union banking app is not automatically the best tool for every money question. The right choice depends on whether the daily task is account control, financial analysis, or long-term planning.
The trade-off between simplicity and breadth
I see the app’s focused role as both a strength and a limitation. A direct banking app can be easier to understand than a crowded financial dashboard filled with accounts, recommendations, and charts. On the other hand, users who want a complete picture of cash flow across several institutions may find that focus restrictive.
This trade-off is important for couples, freelancers, and anyone with multiple income sources. If Navy Federal holds the accounts that matter most, the app may cover the central part of the routine. If it is only one piece of a more complicated setup, I would pair it with another organizational method rather than expecting one app to solve everything.
What switching really involves
Downloading a free app is the easy part. The harder question is whether moving your banking habits to Navy Federal is worth the administrative work. I would first list every direct deposit, recurring bill, subscription, transfer, and emergency payment connected to the old account. Then I would decide whether the Navy Federal relationship is becoming primary or simply remaining an additional place to bank.
I would avoid closing an old account immediately. A safer transition is to keep enough money available for pending payments, update recurring instructions one by one, and review activity during the overlap. This is not a criticism of Navy Federal’s app; it is a realistic cost of changing financial institutions. The app can make the new relationship easier to monitor, but it cannot automatically untangle every outside payment arrangement.
There is also a learning cost. Even a familiar banking layout can place balances, transactions, and account actions differently from the service I used before. I would spend a few minutes identifying the screens I need most often instead of trying to memorize everything on the first day. That preparation pays off when I need information quickly.
Device compatibility belongs in the switching decision too. Since the current version requires Android 11 or newer, owners of older Android phones should check their operating system before making the app central to their banking routine. If the phone cannot run it, a browser-based approach may be the practical fallback, but I would not wait until a payment deadline to discover that limitation.
Who should choose it
I would recommend Navy Federal Credit Union to an existing Navy Federal member who wants convenient mobile access to everyday account information and actions. It is especially suitable for someone who checks transactions regularly, travels, manages recurring payments, or simply prefers handling routine banking from a phone rather than a desktop.
It may also suit a cautious user who wants the direct app for the credit union relationship and is willing to use a separate tool for broader budgeting. That combination is often more realistic than demanding that the bank app provide every possible financial feature. In my view, the strongest setup is the one that gives each tool a clear job.
Who should look elsewhere first
I would hesitate to recommend it as the primary choice for someone who does not have a meaningful Navy Federal relationship. If the goal is to compare banks, manage accounts from many institutions, or build a detailed spending plan, a different category may be more appropriate from the beginning.
I would also steer a user toward alternatives if their main priority is a rich desktop-style financial workspace. A phone app is excellent for short checks, but some people make better decisions when they can see several months of information on a larger screen. In that case, the app can remain useful for quick monitoring without becoming the entire financial system.
My recommendation after weighing the trade-offs
My recommendation is conditional but positive: if you already bank with Navy Federal, I think the app is worth using as your everyday mobile access point. Its free price removes a major barrier, its broad availability makes it easy to adopt, and its purpose is clear. I would use it for quick account checks, transaction reviews, and routine mobile banking, while keeping a separate method for detailed budgeting if I needed one.
I would not choose it solely because it has more than 10 million installs, and I would not reject it solely because its average is 3.7. Those figures provide context, but the decisive factor is fit. The app is most convincing when it shortens the distance between you and your Navy Federal accounts without asking you to turn ordinary banking into a complicated project.
For me, the final test is whether I can imagine opening it during a normal week and getting useful information quickly. I can. The experience is not a universal replacement for multi-bank tools, dedicated budgets, or larger-screen finance work, but that is not its job. If your financial life is centered on Navy Federal, Navy Federal Credit Union is a practical choice for staying connected to it from Android. I would install it, learn the few screens I use most, and judge it by how reliably it supports those real routines.
Best decision rule: choose this app for direct Navy Federal account management; choose another tool when your priority is financial aggregation, deep budgeting, or a broader planning workspace.
Pros
- No monthly maintenance fees on many checking and savings accounts.
- Strong support for military members, veterans, and their families.
- Access to a broad network of fee-free ATMs worldwide.
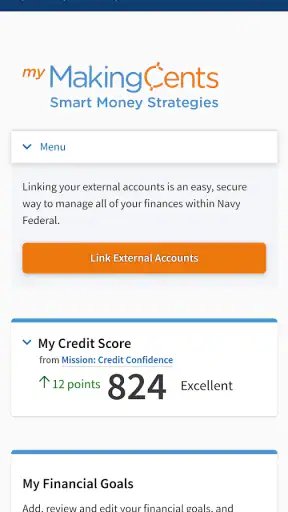
- Useful budgeting tools, alerts, and secure mobile check deposit.
- Competitive loan, mortgage, and certificate rates for eligible members.
Cons
- Membership is limited to eligible service members, families, and select groups.
- Some advanced banking features may feel less polished than major bank apps.
- Cash deposits can be inconvenient without nearby partner locations.
- Certain services and account options vary by membership eligibility.
- International transactions and ATM use may still involve third-party fees.
FAQs for Navy Federal Credit Union
What is Navy Federal Credit Union, and who can join?
Navy Federal Credit Union is a member-owned financial institution offering checking and savings accounts, credit cards, loans, mortgages, and other banking services. Membership is generally available to active-duty, retired, and veteran members of the U.S. military, certain Department of Defense personnel, eligible family members, and household members. Applicants should review the current eligibility requirements before downloading or opening an account.
What can I do with the Navy Federal mobile app?
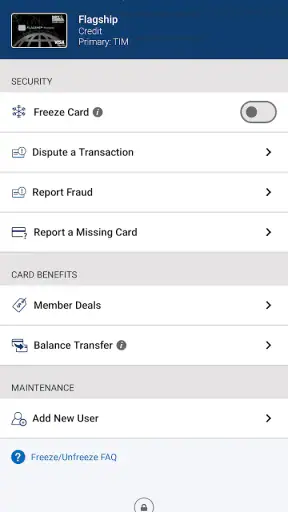
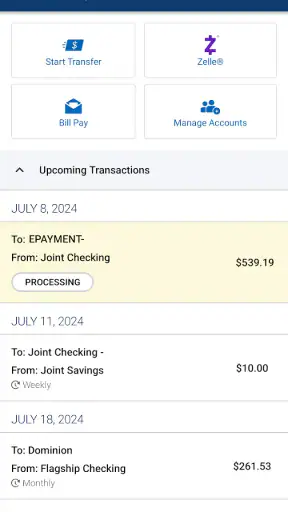
The Navy Federal mobile app lets eligible members manage many everyday banking tasks from an Android or iOS device. Depending on the account and device, users can check balances, review transactions, transfer funds, pay bills, deposit checks by taking photos, manage cards, locate branches or ATMs, and contact support. Available features may vary by account type, location, and app version.
Is the Navy Federal Credit Union app safe to use?
The app includes security features designed to help protect account access and personal information, such as login credentials, device authentication, alerts, and transaction monitoring. However, no banking app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or verification codes.
Are there fees for using Navy Federal’s app and mobile services?
Downloading and using the Navy Federal mobile app is generally not charged as a separate app subscription, but normal account terms and service fees may still apply. Possible charges can involve overdrafts, certain transfers, wire services, replacement cards, or ATM usage outside applicable networks. Fees and limits can change, so check the current fee schedule before relying on a specific feature.
What should I do if I cannot log in or a mobile deposit does not work?
If you cannot log in, confirm that your username, password, and verification details are correct, then use the official recovery options rather than repeatedly guessing credentials. Update the app and check your internet connection if features fail to load. For mobile deposits, use a clear image, endorse the check as instructed, and follow deposit limits and eligibility rules. Contact Navy Federal support through official channels if the issue continues.

Navy Federal Credit Union
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobilehelp@navyfederal.org, visit https://www.navyfederal.org, or review their https://www.navyfederal.org/policy/privacy.html.










